Corporate income tax work for Malaysian tax practices.
Every add-back and deduction carries its statutory reason — such as s33(1), s39(1) or the relevant Public Ruling — and depreciation is reconciled back to the accounts.
Rolls capital allowances forward from last year, reconciles property, plant and equipment, and applies hire-purchase limits, the motor-vehicle cap and small-value asset rules.
Prepares the LHDN Form C figures as an editable draft, each linked to its source, for you to review before you file.
From client files to a reviewed computation, in four steps.
Save your firm and tax-agent profile, start a project, and drop in the client's audited accounts, trial balance, ledger, asset register, CP204 and last year's computation.
Each run checks LHDN's published rates, caps and Public Rulings against TaxCore's register and flags any change. It also tests whether the company is an investment holding company.
It works through the computation phase by phase, flags anything that needs your judgement, and has independent reviewers re-check capital allowances, add-backs and arithmetic.
You receive the computation workbook and a draft Form C. You review them and submit the return yourself, as the tax agent.
TaxCore is made for licensed tax agents preparing company returns. It covers the investment holding test under s60F and s60FA, add-backs with statutory reasons, capital allowances, CP204 instalments and the s107C(10) under-estimation penalty, laid out in your firm's computation format.
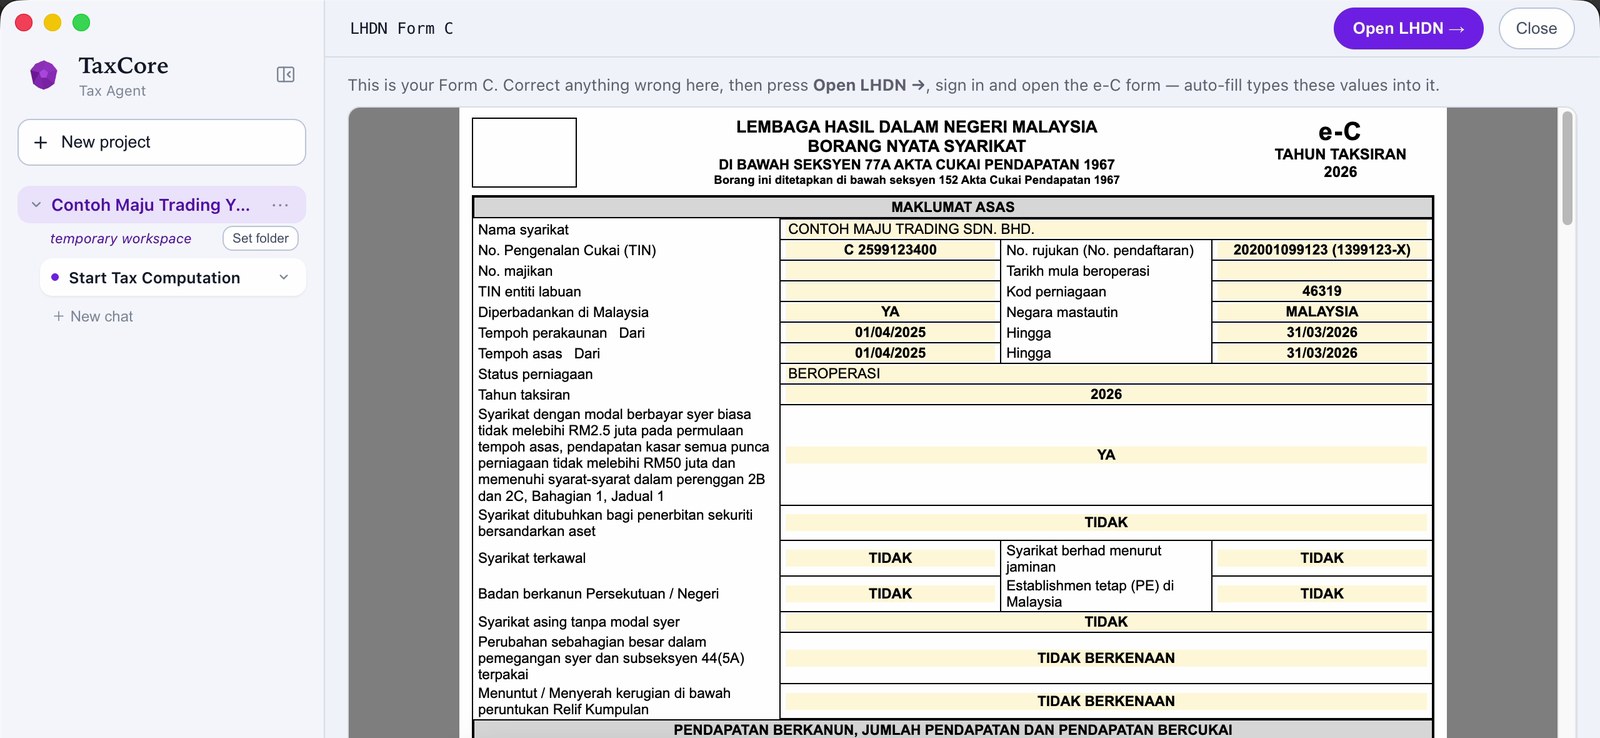
A draft Form C prepared by TaxCore for a sample company.